Market Report
DACH Hotel & Chains Report 2026
October 2026
Branded hotels in Germany, Austria and Switzerland have reached a new high: 4,287 chain hotels with 552,132 rooms now account for 39% of the region's room supply. The DACH Hotel & Chains Report 2026 ranks the leading groups and brands, maps the development pipeline and explains what drives hotel investment and performance across the three markets. Data as of 30 June 2026.
Executive summary
- Branded supply at a record high. The DACH region counts 4,287 chain hotels with 552,132 rooms, 5% more rooms than a year ago. Chain penetration by rooms rose from 36.6% to 39.3%, and the number of hotel brands grew from 373 to 405.
- Germany leads, Austria grows fastest. Branded hotels account for 45.5% of rooms in Germany, 35.6% in Switzerland and 20.7% in Austria. Austria recorded the strongest growth, with chain rooms up 12% to 60,851.
- Accor remains number one. Accor operates almost 60,000 rooms across DACH, followed by IHG Hotels & Resorts (38,369) and Marriott International (37,019). B&B HOTELS is the largest single brand with 27,705 rooms.
- Growth in the value segments. Economy to upper midscale concepts drive expansion. Upper midscale is the largest scale, with 156,107 branded rooms, while serviced apartment operators such as limehome, SMARTments and numa gain ground.
- A tighter pipeline. Rooms under construction fell from around 30,000 to about 29,000. Construction prices rose by about 5% in twelve months and construction loan rates stand at 3.6 to 4.2%. Berlin, Hamburg and Vienna lead the pipeline.
- Investment is back. Hotel transaction volume reached €1.84 billion in Germany in 2025 (+40%), around €480 million in Austria (+43%) and a record of about €428 million in Switzerland.
- Operator distress reshapes the market. The break-up of Revo Hospitality and the insolvencies of Lindner Hotels and ACHAT Hotels have opened a wide window for conversions and brand market entries. Lenders now expect equity of at least 30%, tending towards 40%, for projects relying on white-label operators.
- Success beyond the A-cities depends on demand structure. In B, C and D locations, hotels perform best when meeting capacity, an online reputation score above 8.0 and at least two independent demand generators come together.
Download the report
1. The DACH hotel market in 2026
Four in ten hotel rooms in the DACH region now belong to a chain. As of 30 June 2026, 4,287 chain hotels with 552,132 rooms operate across Germany, Austria and Switzerland, an all-time high. Chain penetration by rooms rose from 36.6% to 39.3% within a year.
The overall market is moving in the opposite direction. Total supply shrank slightly to 43,658 hotels and 1,406,087 rooms, while the average hotel still has only 32 rooms. Independent hotels continue to hold the majority of supply, particularly in secondary cities and leisure destinations. In the major cities, however, chains already account for 50 to 60% of room capacity.
Demand provides a solid base. Overnight stays in the DACH region rose by 0.8% in 2025 and set a record in all three countries. The economic backdrop is mixed: Germany returned to modest growth of 0.2% and Austria of 0.6%, while Switzerland again outperformed its neighbours.
Germany holds 80% of the region’s chain rooms, Austria 11% and Switzerland 9%. Berlin, Munich, Vienna, Frankfurt/Main and Hamburg alone account for around 178,000 branded rooms, almost a third of the DACH total.
2. Pipeline: fewer rooms under construction
The DACH pipeline is shrinking. Rooms under construction fell from around 30,000 to about 29,000 within a year. After moderating in 2024 and 2025, construction prices picked up again in 2026, rising by around 5% over twelve months. Construction loan rates increased by 0.3 to 0.5 percentage points between August 2025 and August 2026 and now range from 3.6 to 4.2%.
Berlin leads the pipeline with 32 hotels and 3,218 rooms, followed by Hamburg with 40 hotels and 2,959 rooms and Vienna with 17 hotels. Leipzig has dropped out of the DACH top ten and, as in 2025, Cologne is not represented. Bochum has re-entered the ranking with three hotels.
3. Transactions and institutional investors
Hotel investment in the DACH region has clearly recovered since 2024. In Germany, transaction volume reached around €1.84 billion in 2025, 40% more than in 2024 and above the five-year average for the first time since 2022. The number of deals rose by about 39% to 64. High-net-worth individuals and family offices accounted for 29% of volume, institutional investors for around 27%.
Operator distress has been the other defining feature. The break-up of Revo Hospitality, whose more than 150 hotels are moving to other operators, and the insolvencies of Lindner Hotels and ACHAT Hotels have opened an unusually wide window for international brands to enter or grow. Sunday Hotels and B&B HOTELS took over the leases and management contracts of 24 and nine former Revo hotels respectively. As a result, chain groups expanded mainly through rebranding and conversion rather than new builds.
Financing has become more available but more selective. Senior debt is typically offered at loan-to-value ratios of 55 to 65%. For projects that rely on a white-label operator, lenders now expect equity of at least 30%, tending towards 40%. In the first half of 2026, German transaction volume reached around €741 million, 18% below the exceptionally strong first half of 2025; a full-year volume of around €2 billion is considered realistic.
In Austria, transaction volume rose by 43% to around €480 million in 2025, with roughly four fifths concentrated in Vienna. International buyers, mainly from Germany and Switzerland, accounted for about 77% of volume. In Switzerland, hotel transactions reached a record of about €428 million, led by trophy assets such as The Alpina Gstaad; institutional capital is returning, as the acquisition of the Zurich Marriott Hotel shows.
4. DACH rankings: who leads the market
Accor remains the undisputed market leader with 414 hotels and 59,505 rooms across DACH. IHG Hotels & Resorts follows with 38,369 rooms, ahead of Marriott International with 37,019 rooms, which grew by 10%. The largest DACH-based groups are Motel One, H-Hotels and Dorint (DHI Dorint Hospitality & Innovation).
Among the brands, B&B HOTELS leads with 265 hotels and 27,705 rooms, followed by Motel One (21,003 rooms) and Trademark Collection by Wyndham (15,029 rooms). Premier Inn shows the strongest growth in the top ten, with rooms up 17%.
Growth is concentrated in the economy to upper midscale segments, driven by limited-service concepts such as B&B HOTELS, ibis and Premier Inn. Most supply remains in the midscale to upscale segments. Established brands such as Motel One, Mercure, Best Western and ibis increasingly compete with serviced apartment operators including limehome, SMARTments and numa.
5. Germany: 45% of hotel rooms are branded
Germany is by far the largest chain market in the region, with 3,216 chain hotels and 440,231 rooms. Chain penetration by rooms rose from 43.1% to 45.5%. Around 59% of chain rooms belong to international brands, and the market is dominated by midscale, upper midscale and upscale hotels.
Demand remains stable but price-sensitive. Germany recorded 497.5 million overnight stays in 2025 (+0.3%), driven by domestic travellers (+0.7%), while international overnights fell by 1.8% after the UEFA EURO 2024 effect. In the first five months of 2026, overnight stays rose by 1.3%. At the same time, real hotel revenues fell by 2.0% in 2025 while nominal revenues rose by 0.8%. With 30.3 insolvencies per 10,000 companies in the first quarter of 2026, hospitality recorded the second-highest rate of all industries.
Accor remains the largest chain group with 43,254 rooms, followed by IHG Hotels & Resorts and Marriott International. Whitbread (Premier Inn) grew fastest with rooms up 19%. Motel One climbed to sixth place, BWH Hotels dropped to seventh, Fattal Hotels Group entered the top ten and Radisson Hotel Group left it.
The seven largest cities host more than 1,050 chain hotels with around 189,700 rooms, led by Berlin (49,207 rooms), Munich (38,862) and Frankfurt/Main (29,801). Yet more than 56% of the rooms in the pipeline are located outside these cities, as chains push into secondary and tertiary markets. Union Investment is the largest institutional owner with 46 hotels and 11,571 rooms.
Market insight: The industrialisation of hospitality
Between 2000 and 2024, revenue in the German hotel industry grew from around €15 billion to around €35 billion, while overnight stays rose from around 200 million to around 300 million. From 2014 to 2024, the number of hotels fell from about 20,000 to 19,000, while the average size rose from 39 to 46 rooms. The economy segment’s share of hotel investment volume grew from around 5% in the mid-2010s to around 11% in 2025.
“Brand architecture increasingly serves operational and distribution purposes rather than direct customer differentiation.” — Prof. Dr. Christian Buer, Managing Partner, Horwath HTL Germany
6. Austria: chain rooms up 12% in one year
Austria is the fastest-growing chain market in the region. The number of chain hotels rose by almost 11% to 535, and chain rooms by 12% to 60,851. With 20.7% of rooms under a brand, penetration nevertheless remains the lowest in DACH, as independent and family-run hotels hold 79.3% of the roughly 294,000 rooms.
International chains concentrate in Vienna, where total supply now comprises around 450 hotels and 42,500 rooms, about 8,000 more rooms than before the pandemic. Vienna also leads the pipeline with 17 hotels. Accor is the largest chain group with 39 hotels and 5,670 rooms, followed by Marriott and Hilton. JUFA Hotels leads the domestic chains and the brand ranking with 48 hotels and 2,605 rooms.
Brand growth is now driven by distressed assets and third-party operators rather than new franchise partnerships. The Andaz Vienna am Belvedere was sold out of the Signa insolvency for €92 million and reopened as Hyatt Regency Vienna under MHP Hotel AG in April 2026. Mandarin Oriental entered Austria in December 2025, while the Revo Hospitality insolvency placed eleven Austrian hotels under restructuring.
Market insight: Record demand, pressure on margins
Austria reached a record 157.29 million overnight stays in 2025, and Vienna exceeded 20 million for the first time. From January to July 2026, overnight stays rose by another 1.8%, with Vienna up 5% and Upper Austria up 9.3%. Profitability is under pressure: employee costs exceed 36% of operating revenue, and inflation-adjusted daily spending per guest is around 85% of the pre-pandemic level. The market is shifting towards quality tourism, alpine wellness, premium chalets and efficient city hotels.
— Brigitte T. Gruber, Managing Partner, Horwath HTL Austria
7. Switzerland: more than a third of rooms are branded
Switzerland counts 536 chain hotels with 51,050 rooms, 3% more than a year ago. Chain penetration by rooms rose from 34.2% to 35.6%. Domestic and international chains each operate 268 hotels, but international brands hold around two thirds of chain rooms.
Demand reached new records. Swiss hotels recorded 43.93 million overnight stays in 2025 (+2.6%), with foreign guests up 3.7% and domestic guests up 1.4%. The 2025/26 winter season added another record of 18.75 million overnight stays. SECO expects GDP growth of 0.9% in 2026, dampened by higher energy prices and geopolitical tensions.
Accor leads with 10,581 rooms, ahead of Marriott International, which grew its rooms by 21%. The largest domestic groups are Michel Reybier Hospitality, Davos Klosters Bergbahnen and Hotels by Fassbind. Geneva (7,931 rooms) and Zurich (7,640) are the largest chain destinations, and Geneva also leads the pipeline with 1,346 rooms. UBS Asset Management is the largest institutional owner with 3,066 rooms.
8. Market insight: what makes B, C and D locations successful?
Hotel success outside the A-cities depends on the structure of local demand, not on the location class itself. Rising land and construction costs and saturation in the major cities are shifting development towards B, C and D locations. A study by Horwath HTL in collaboration with Heilbronn University, using Dresden, Kiel and Villingen-Schwenningen as case studies, shows what makes these markets work.
Class B locations rest on several demand pillars such as corporate, MICE and city tourism. Class C locations operate on a narrower, regional base. Class D locations typically depend on a single driver such as an industrial cluster, a hospital or a leisure attraction, which concentrates both opportunity and risk. No segment is superior everywhere, but the midscale segment proves the most adaptable.
Performance rests on three conditions that only work together:
- Meeting and conference capacity, assessed via TRevPAR rather than RevPAR, because ancillary revenue makes the decisive contribution.
- An online reputation score above 8.0, the entry threshold for competitive distribution.
- Proximity to at least two independent demand generators, so that the weakening of one source does not hit overall performance.
Where only one or two conditions are met, the performance advantage largely disappears. Brand strategy follows the same logic: in B locations, professional independent management can partly offset a brand’s distribution power, while in C and especially D locations, brand-driven distribution is hard to replace.
For investors, this means evaluating total revenue potential and conference capability rather than room revenue alone. Operators should align concept and segmentation with local demand generators, and developers should prioritise locations served by several independent sources of demand.
Horwath HTL DACH advisory team
The Horwath HTL DACH Advisory Team provides strategic hotel consulting, feasibility studies, transaction advisory, operator selection, and market valuation services across Germany, Austria, and Switzerland. As primary authors of the annual DACH Hotel & Chains Report, the advisory group specializes in tracking hotel pipeline developments, white-label operator performance, and chain penetration metrics across German-speaking Europe.
Core advisory capabilities
- Hotel Feasibility & Best-Use Studies: Independent market demand analyses, financial forecasting, and site suitability assessments for single-asset and portfolio developments in A, B, C, and D locations.
- Transaction Advisory & Valuation: Commercial due diligence, property asset valuation, loan-to-value structuring support, and institutional acquisition consulting.
- Operator & Brand Selection: Management contract negotiations, lease contract structuring, and operator search for franchise, direct, and white-label hotel brands.
- Strategic Asset Restructuring: Turnaround advisory, operator transition management, and repositioning strategies for distressed hotel assets.
Geographic advisory coverage
Our DACH hospitality advisory hubs operate from Frankfurt and Vienna, offering regional coverage across major metropolitan markets (Berlin, Munich, Hamburg, Vienna, Zurich, Geneva) as well as secondary, tertiary, and resort destinations throughout Germany, Austria, and Switzerland.
DACH Hotel & Chains Report 2026 authors
The DACH Hotel & Chains Report 2026 was researched and authored by senior hospitality advisors from Horwath HTL Germany and Horwath HTL Austria:
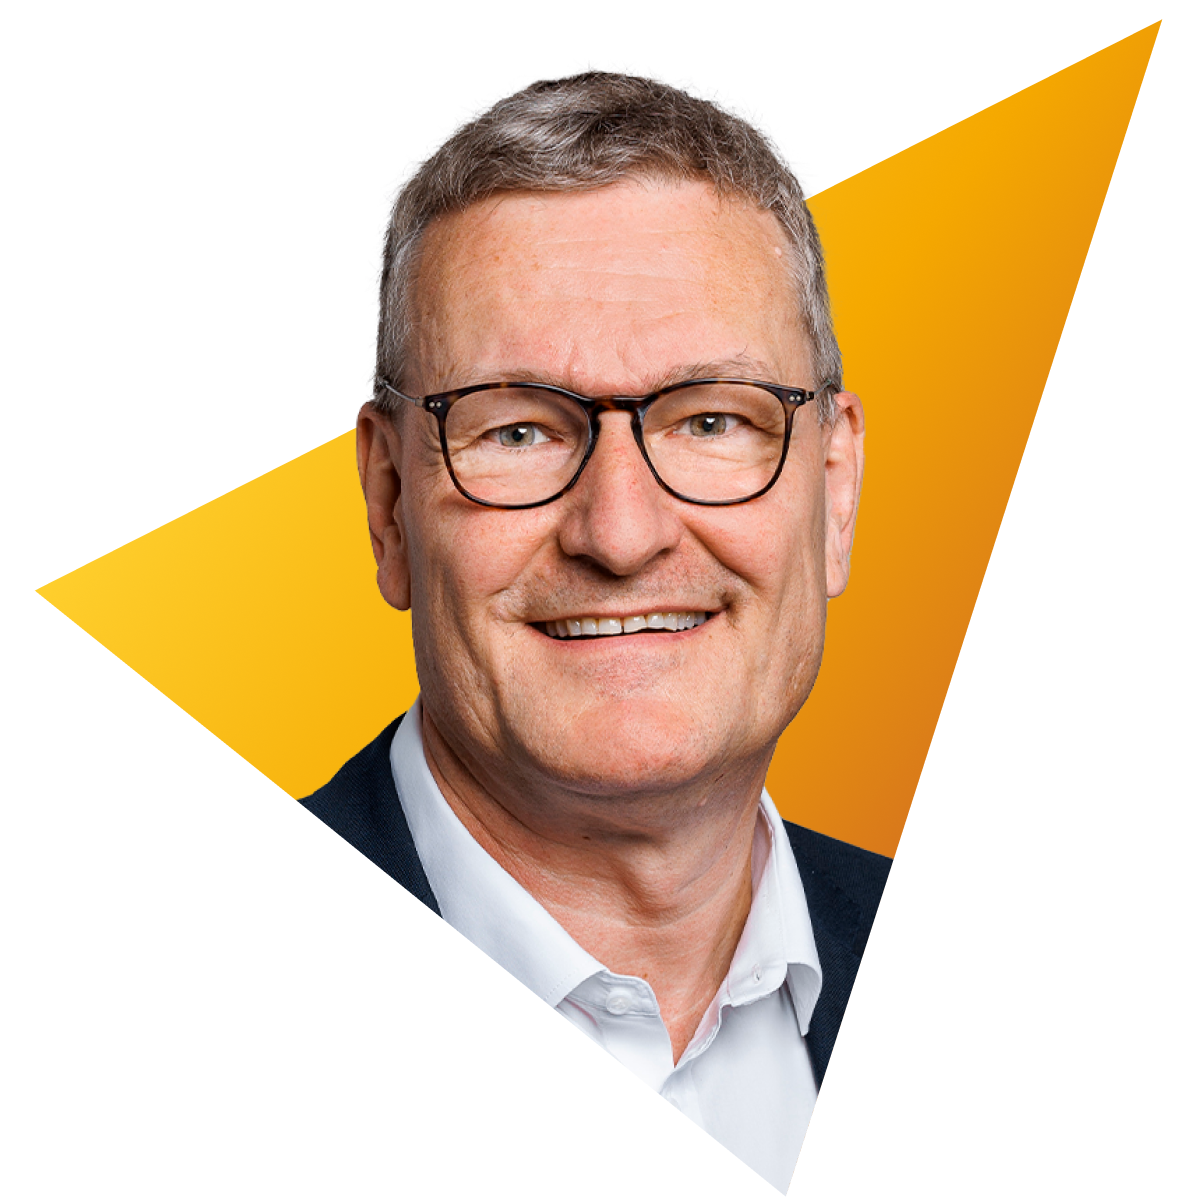
Prof. Dr. Christian BuerRole: Managing Partner, Horwath HTL Germany Prof. Dr. Christian Buer is the Managing Partner of Horwath HTL Germany. With over three decades of executive experience in hotel development, asset management, and academic research, he advises institutional investors, lenders, and family offices on complex hotel transactions, operator contract structuring, and portfolio strategy. He also leads research on the industrialisation of hospitality and structural shifts in brand architecture across European hotel markets. Contact Prof. Dr. Christian Buer: |
 |
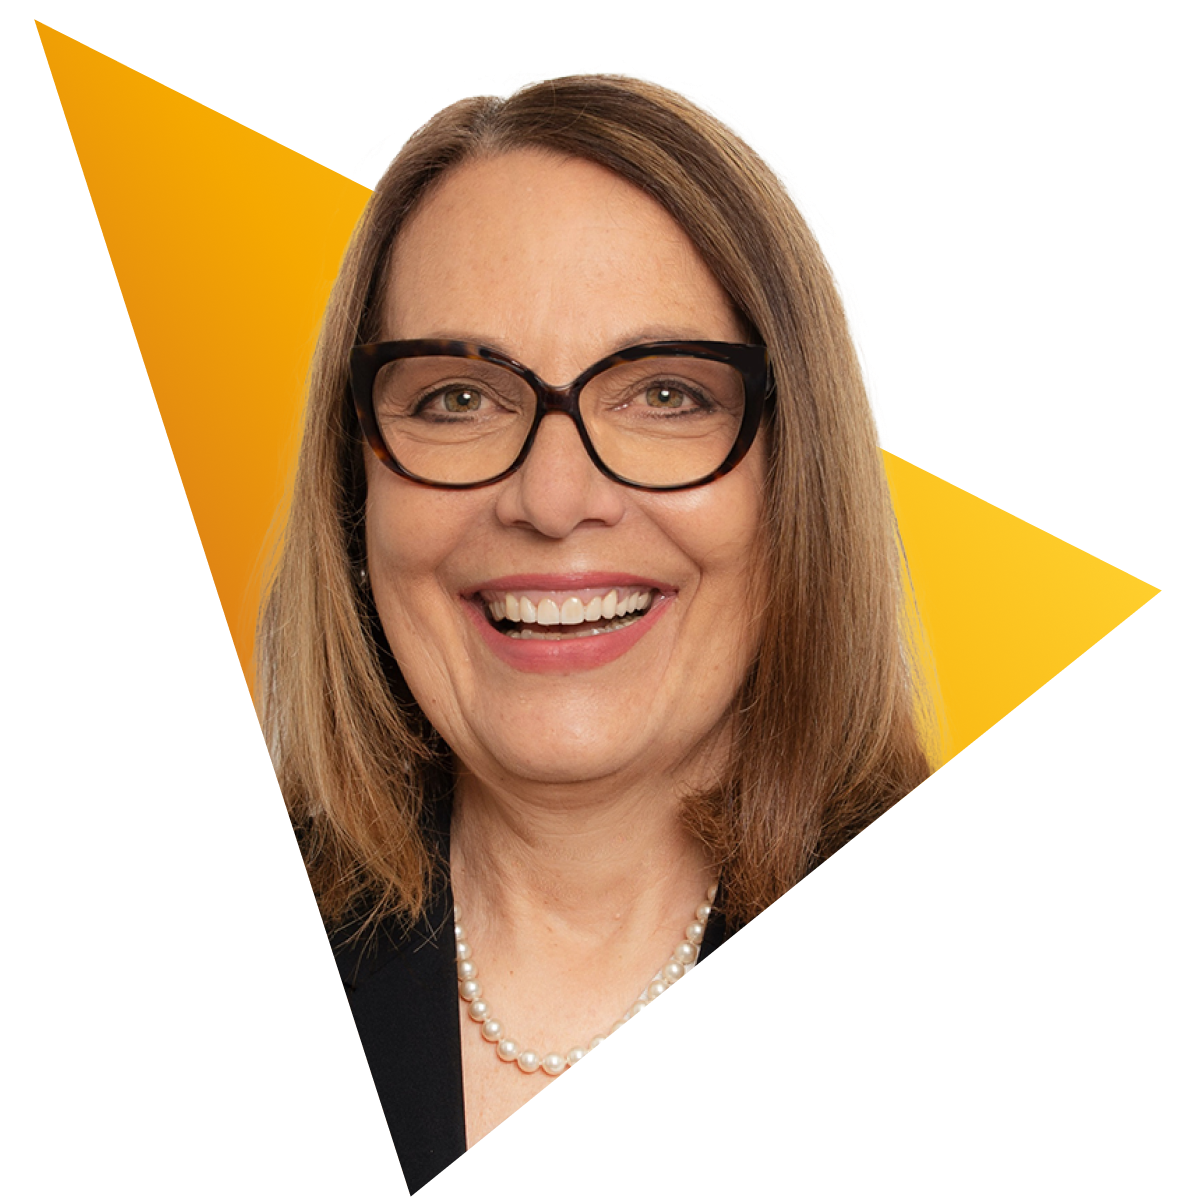
Brigitte T. Gruber, MBARole: Managing Partner, Horwath HTL Austria Brigitte T. Gruber, MBA, serves as Managing Partner of Horwath HTL Austria in Vienna. She is a recognized authority on Austrian and CEE hotel real estate, leisure resort performance, and operator contract negotiations. Her advisory work covers alpine luxury wellness developments, urban city hotel performance in Vienna, and turnaround solutions for distressed hotel assets across Austria. Contact Brigitte T. Gruber: |
 |
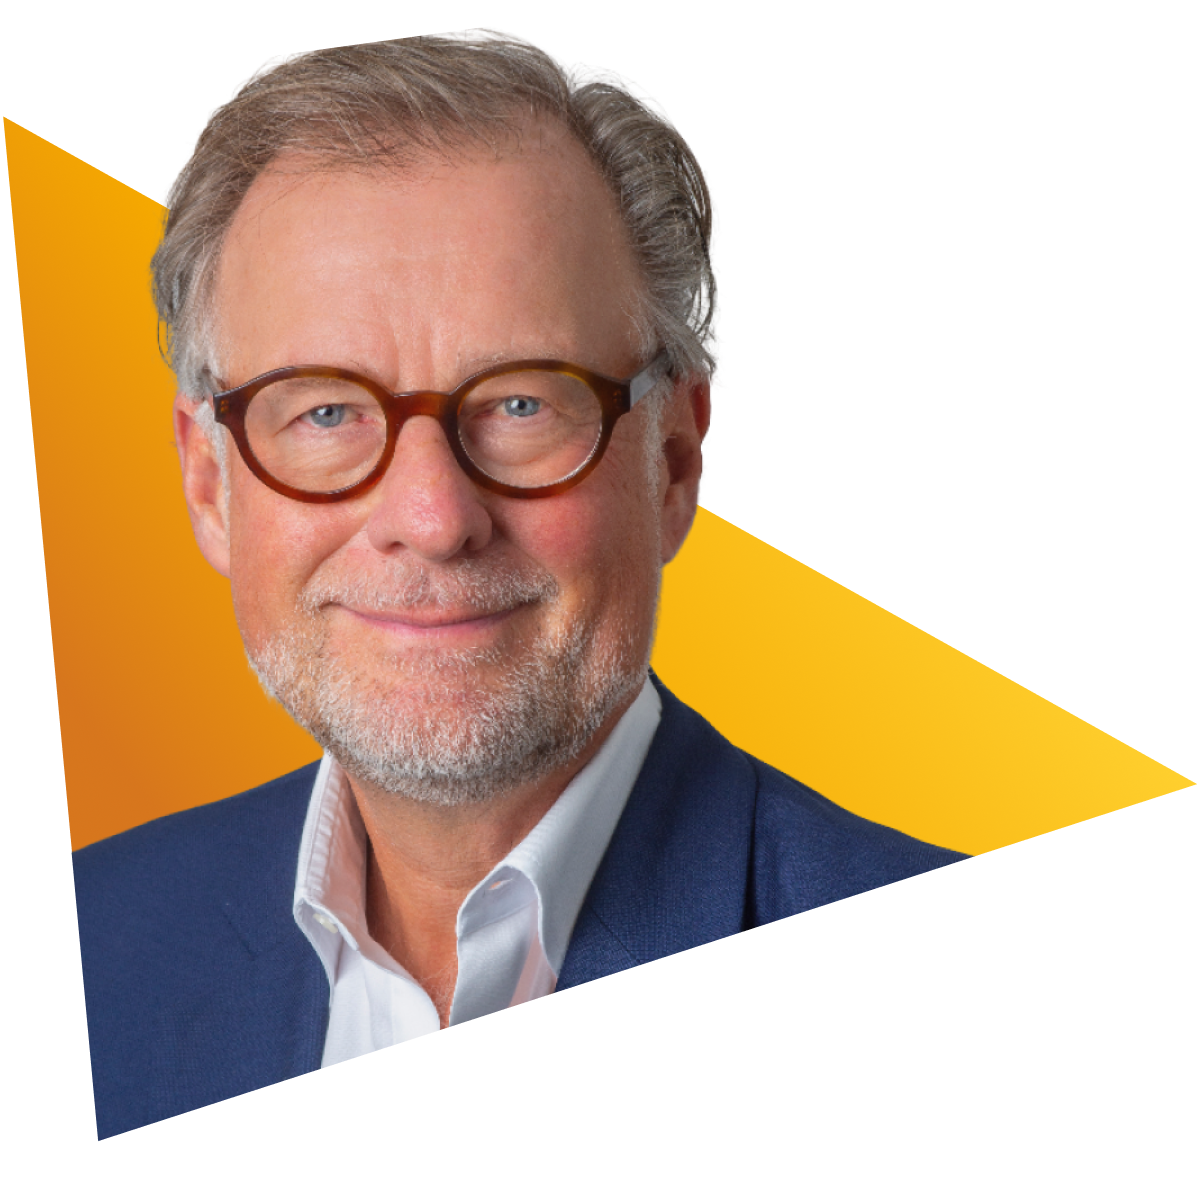
Andrea JörgerRole: Managing Partner, Horwath HTL Switzerland Primary Focus: Andrea is a hospitality and real estate professional with 35 years of experience in hotel operations, development, asset management, and transactions. He advises investors, developers, and operators on hotel and mixed-use projects, with particular expertise in project management, operator search, and negotiations. As overall project manager for The Circle, the CHF 1 billion development at Zurich Airport, he led key development phases and the operator selection and agreements with Hyatt. He holds a Master’s Degree in Global Hospitality Business from EHL Hospitality Business School. Contact Andrea Jörger: |
 |
Frequently asked questions
How many chain hotels are there in the DACH region in 2026?
As of 30 June 2026, there are 4,287 chain hotels with 552,132 rooms in Germany, Austria and Switzerland. That is 6% more hotels and 5% more rooms than in 2025.
What is the chain penetration in Germany, Austria and Switzerland?
Measured by rooms, 45.5% of hotel supply in Germany is branded, 35.6% in Switzerland and 20.7% in Austria. Across the DACH region, penetration rose from 36.6% to 39.3% within a year.
Which is the largest hotel group in the DACH region?
Accor is the largest hotel group with 414 hotels and 59,505 rooms, followed by IHG Hotels & Resorts with 38,369 rooms and Marriott International with 37,019 rooms.
Which is the largest hotel brand in the DACH region?
B&B HOTELS is the largest brand with 265 hotels and 27,705 rooms, ahead of Motel One with 21,003 rooms and Trademark Collection by Wyndham with 15,029 rooms.
Which cities have the largest hotel pipeline?
Berlin leads the DACH pipeline with 32 hotels and 3,218 rooms, followed by Hamburg with 40 hotels and 2,959 rooms and Vienna with 17 hotels. In Switzerland, Geneva leads with 1,346 rooms in the pipeline.